Unmasking Inequality: Discriminatory Mortgage Rates in the Housing Market
Discriminatory Mortgage Rates: Unearthing Inequality in the Housing Market
Introduction:
The housing market is a vital component of any society, providing individuals and families with shelter and stability. However, for many years, discriminatory practices have plagued this sector, resulting in unequal access to mortgage rates for certain marginalized communities. This article aims to shed light on the issue of discriminatory mortgage rates and explore its implications on affected populations. By examining historical context, current challenges, and potential solutions, we can better understand how to address this pervasive problem.
Understanding Discriminatory Mortgage Rates:
1. Historical Context:
To comprehend the roots of discriminatory mortgage rates, one must delve into the history of housing discrimination. Redlining is a system that emerged in the mid-20th century when federal agencies designated neighborhoods based on perceived riskiness for lending purposes. These designations disproportionately targeted minority communities such as African Americans and Hispanic Americans by labeling their neighborhoods as high-risk areas. Consequently, residents in these neighborhoods faced limited access to fair mortgage rates or were entirely denied mortgages.
2. Contemporary Challenges:
Despite significant progress since redlining was officially outlawed through the Fair Housing Act of 1968 in the United States (similar laws exist globally), discriminatory practices still persist today under different guises.
a) Disparities Based on Race:
Studies continue to reveal disparities in interest rates offered to borrowers based on their racial background. A comprehensive analysis conducted by Reveal from The Center for Investigative Reporting found that African American applicants were 2.4 times more likely than white applicants to receive higher interest rate loans.
b) Socioeconomic Factors:
Discrimination extends beyond race alone; socioeconomic factors also play a role in determining who receives favorable mortgage rates. Low-income individuals often face additional barriers due to limited financial resources or credit histories impacted by systemic inequalities.
c) Predatory Lending:
Another challenge affecting marginalized communities is predatory lending practices that target vulnerable borrowers. These practices involve offering subprime loans with higher interest rates and unfavorable terms, disproportionately affecting minority communities.
Implications of Discriminatory Mortgage Rates:
1. Generational Wealth Gap:
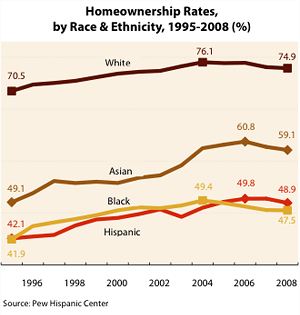
Discriminatory mortgage rates contribute to the perpetuation of the generational wealth gap. Limited access to fair lending prevents marginalized communities from building equity and accumulating wealth through homeownership. This disparity exacerbates existing economic inequalities between racial and socioeconomic groups.
2. Housing Insecurity:
Unfair mortgage rates result in housing insecurity for affected populations, making it challenging for individuals and families to find stable housing options. When high-interest rates are combined with other systemic barriers, such as limited affordable housing availability, marginalized communities face increased vulnerability to displacement or homelessness.
3. Community Disinvestment:
Discriminatory mortgage practices discourage investment in historically marginalized neighborhoods by financial institutions and potential homebuyers alike. The resulting lack of resources and infrastructure exacerbates social inequities within these communities, perpetuating cycles of poverty and limited opportunities for growth.
Addressing Discriminatory Mortgage Rates:
1. Policy Reforms:
To combat discriminatory mortgage practices effectively, policymakers must enact reforms that promote fair lending standards across all demographics. Implementing stricter regulations against predatory lending practices is crucial to protect vulnerable borrowers from exploitative loans with exorbitant interest rates.
2. Education and Financial Literacy Programs:
Improving financial literacy among marginalized communities can empower individuals to navigate the complexities of mortgages successfully while identifying unfair lending practices or discriminatory treatment by lenders.
3. Increased Transparency:
Enhancing transparency within the lending industry can aid in identifying disparities based on race or socioeconomic factors more easily. Requiring lenders to disclose data related to loan approvals, denials, interest rates offered, and borrower characteristics would enable regulatory bodies to monitor potential discrimination more effectively.
4. Community Development Initiatives:
Investing in community development initiatives aimed at revitalizing historically disinvested neighborhoods can create an environment conducive to fair lending practices. Collaborative efforts involving local governments, community organizations, and financial institutions can help promote homeownership opportunities for marginalized communities.
Conclusion:
Discriminatory mortgage rates persist as a significant obstacle for marginalized populations seeking homeownership and economic stability. Understanding the historical context, contemporary challenges, and potential solutions is vital in addressing this issue effectively. Through policy reforms, education programs, increased transparency, and community development initiatives, we can strive towards a housing market that offers equal opportunities to all individuals regardless of their race or socioeconomic background. By unearthing inequality in the mortgage industry and working collectively to dismantle discriminatory practices, we pave the way for a more equitable future.