Unearthing Discrimination: Exposing Unfair Practices in Mortgage Lending
Discrimination in Mortgage Lending: Unearthing an Unfair Practice
Welcome back, fellow metal detecting enthusiasts! Today, we are taking a break from discussing the latest gadgets and treasures to shed light on an important issue that affects many individuals seeking homeownership – discrimination in mortgage lending.
When it comes to buying a home, securing a mortgage is often necessary for the majority of buyers. However, studies have shown that discriminatory practices still persist within the lending industry, which can greatly impact certain groups’ access to affordable housing.
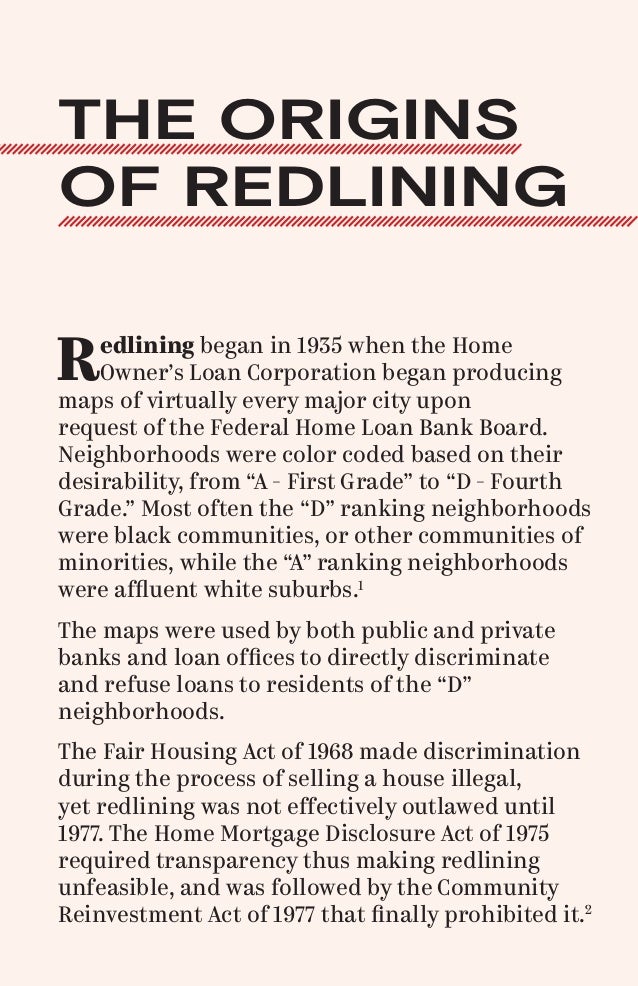
Historically, discrimination in mortgage lending has disproportionately affected minority groups such as African Americans and Hispanics. This unfair practice dates back decades when redlining policies were prevalent. Redlining involved marking off certain neighborhoods based on racial demographics and denying loans or charging higher interest rates to residents residing within those areas.
While redlining is now illegal thanks to the Fair Housing Act of 1968, other forms of discrimination continue to exist. One such practice is known as “reverse redlining.” In this scenario, lenders target communities predominantly populated by minority groups with predatory loans featuring high-interest rates and unfavorable terms. These borrowers may be denied access to more affordable mortgages offered elsewhere due to their race or ethnicity.
Another form of discrimination occurs through steering – when loan officers direct borrowers towards specific loan products based on their race or ethnicity rather than considering their financial qualifications. For example, a white borrower might be encouraged towards conventional loans with lower interest rates while minorities are directed toward subprime loans with higher costs.
Even beyond racially-based discrimination in mortgage lending, other factors such as gender identity or sexual orientation can also play a role in determining access to fair mortgages. LGBTQ+ individuals may face additional hurdles when applying for loans due to biases held by some lenders.
To combat these discriminatory practices and promote fair lending opportunities for all potential homeowners regardless of race, ethnicity or any other characteristic protected under federal law (such as gender identity), comprehensive regulations must be implemented and enforced. Lending institutions must adopt policies that provide equal opportunities to all borrowers, regardless of their background, financial situation, or personal attributes.
Additionally, education is crucial in raising awareness about discrimination in mortgage lending. Borrowers should understand their rights and be equipped with the knowledge to identify any signs of discriminatory practices. Organizations like the Consumer Financial Protection Bureau (CFPB) offer resources for individuals facing unfair treatment in the lending process.
As metal detecting enthusiasts who appreciate history and preserving relics from the past, it is essential that we also work towards a fairer future for everyone. Discrimination has no place in our society, especially when it comes to something as fundamental as homeownership.
Let’s continue advocating for transparency, accountability, and equal access to mortgages so that every individual has a chance to unearth the joy of owning their own home – free from discrimination.